The Summary
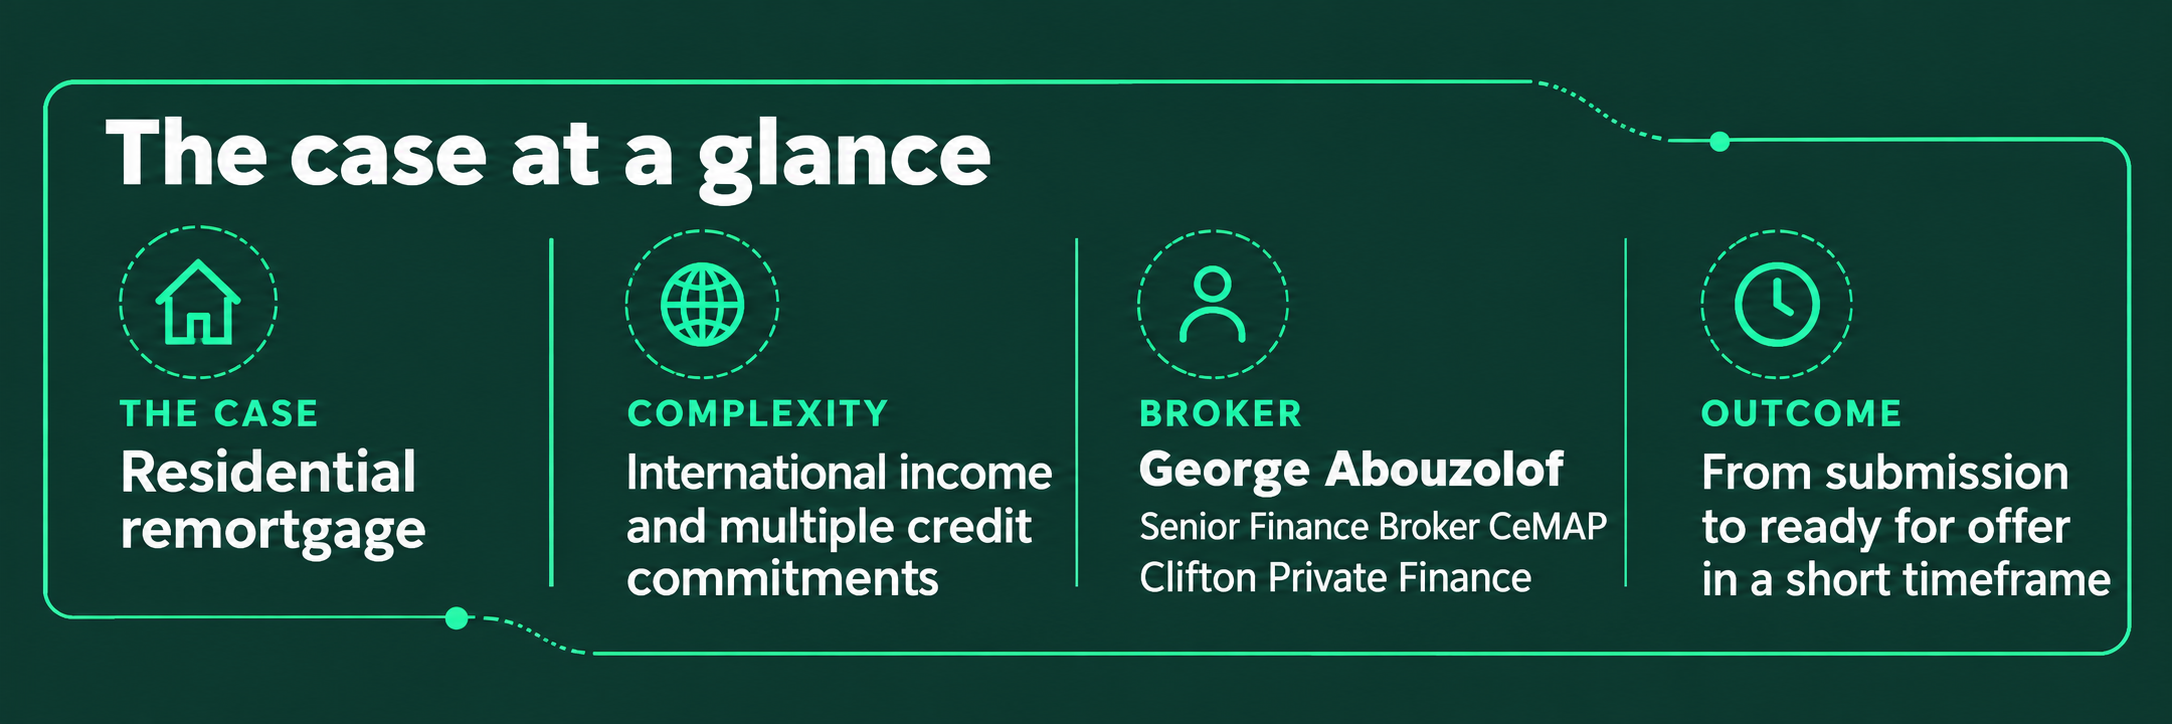
A complex residential remortgage involving international income and multiple credit commitments provided a real-world test of Dudley Building Society’s new mortgage platform. For broker George Abouzolof, the experience was defined by clearer information requirements, less manual work and direct access to the underwriter when needed.
The result was a complex case progressing smoothly from submission to ready for offer, with George describing the new system as significantly more user-friendly and saying he was surprised by how quickly the application progressed.
A real test for the new mortgage journey
Mortgage technology is often judged by what it can automate, but for brokers the more meaningful test is usually much simpler: does it make it easier to get a real customer with real circumstances to an answer?
For George Abouzolof, Senior Finance Broker CeMAP at Clifton Private Finance, an international residential remortgage placed with Dudley Building Society provided an early example of the difference the Society’s new mortgage origination platform can make.
The client
The case involved customers with an international income profile who were looking to remortgage their residential property and raise additional finance to consolidate a number of unsecured credit commitments. The unsecured borrowing had accumulated over time for a variety of personal expenditure requirements.
For George, their experience is understandable and increasingly familiar. Unsecured finance can be arranged quickly and easily, sometimes through an online application completed in minutes, whereas raising money through a remortgage inevitably involves advice, underwriting, a valuation and solicitors.
That convenience can often create a more complicated refinancing requirement later, and in this instance there were multiple accounts that needed to be consolidated.
Why Dudley?
Many mainstream lenders are not geared towards applications involving customers with overseas income, while specialist lenders can have their own criteria around international circumstances. In this case, the application fell within Dudley Building Society’s lending appetite.
There were additional considerations too. A number of lenders impose limits on the amount of unsecured debt they will allow a customer to consolidate. Dudley’s approach made the case suitable within its lending criteria, helping make it an appropriate solution for this application.
Making a complex case easier to package
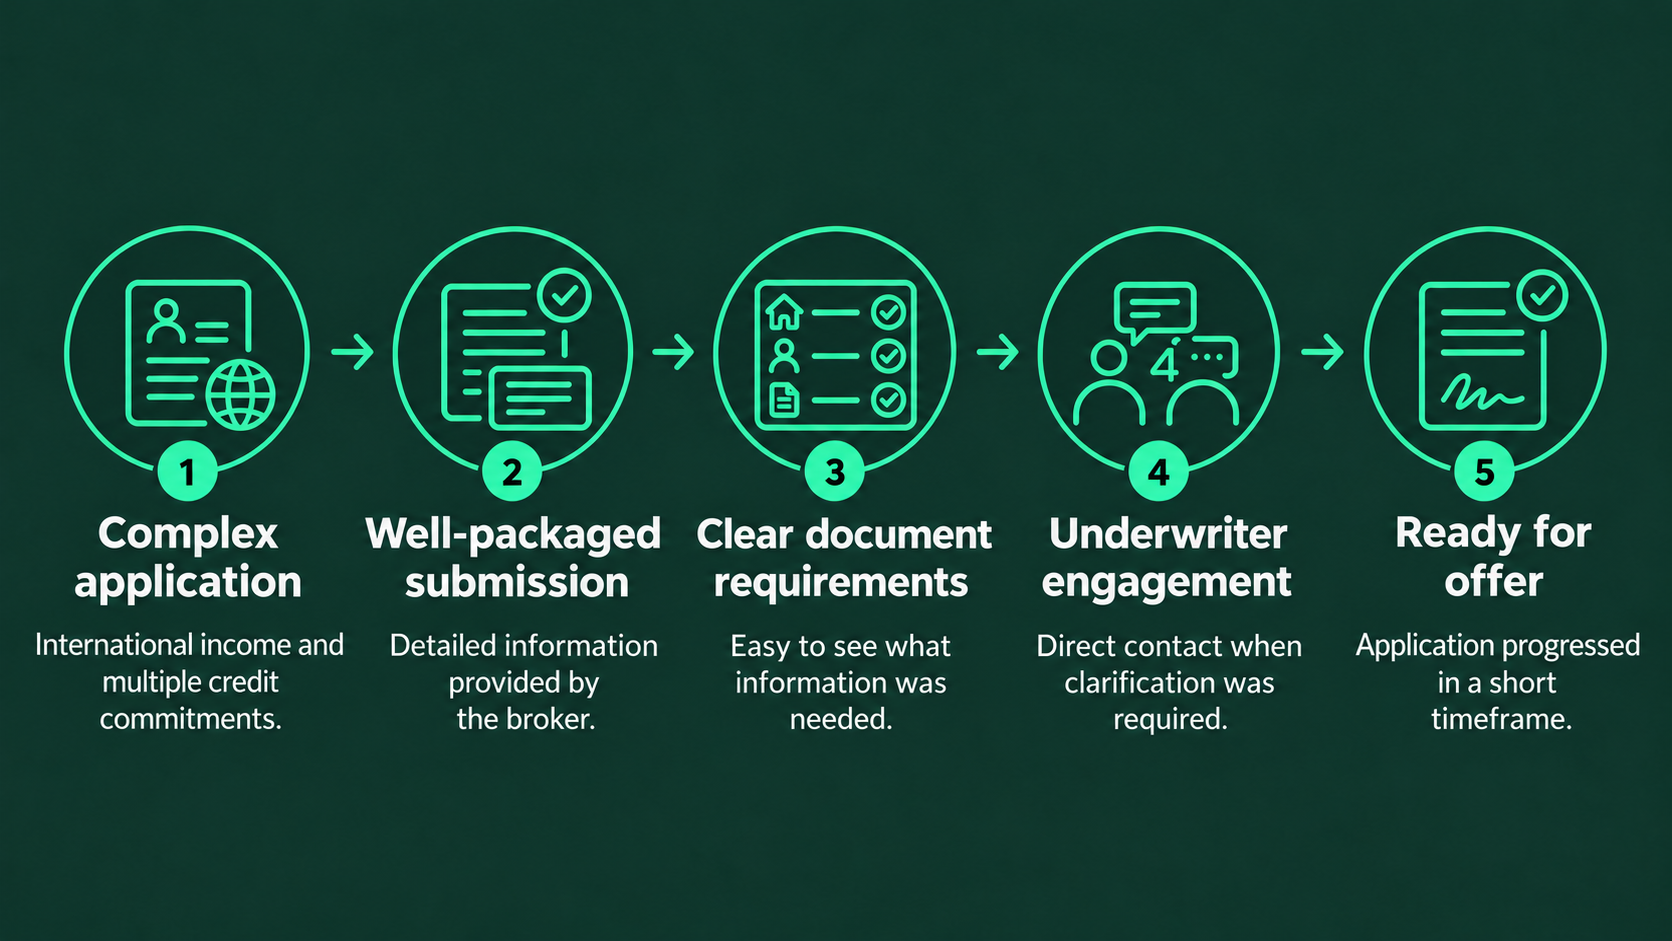
The complexity of the case also meant that good packaging mattered. With multiple accounts being consolidated, George provided a detailed supporting letter setting out the background to the application and identifying each account so that the underwriter could reconcile the information against the statements being uploaded.
George is clear that technology cannot replace the broker’s responsibility to submit a properly packaged case. Efficiency has to work both ways. A poorly prepared application will inevitably generate questions however good the lender’s technology might be. What the technology can do is make the subsequent journey much easier.
George had not known that Dudley Building Society had introduced a new system until he came to submit the application, but immediately found it a significant improvement on the previous experience.
In his words, it was “a much more user-friendly system to use.” That mattered particularly for an application involving international circumstances. Non-standard income arrangements and circumstances outside the standard UK residential mortgage journey will often expose the limitations of older case management systems. George’s experience was that Dudley’s new platform had clearly been developed in a way that made dealing with more bespoke circumstances easier.
Clearer requirements, less friction
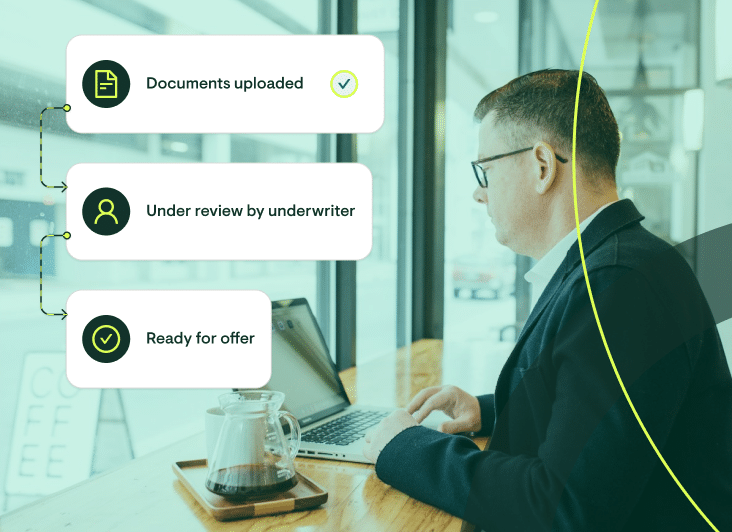
Some of the documents initially uploaded required additional information to follow, but the new process made those requirements clearer and involved less manual work for the broker.
For George, that is where the combination of technology, underwriting and good broker packaging becomes important. The broker needs to provide the information necessary to explain the case properly, while the lender needs to understand that information and avoid returning with questions that could have been answered from the material already supplied.
Get both sides of that equation right and the customer feels the difference too. Dudley’s technology also sits alongside the human relationship rather than replacing it. George was contacted directly by the underwriter handling the application when additional information or clarification was required, helping maintain clear communication throughout the process. That combination removes unnecessary administration while ensuring direct engagement remains available when judgement or discussion is needed.
From submission to ready for offer
The application progressed from submission to ready for offer within a short timeframe. For a relatively complex application involving overseas income and the consolidation of multiple unsecured credit commitments, the speed of the process was noticeable. George was “rather surprised” by how quickly the application progressed while the clients themselves were very happy with Dudley and the speed of the process.
The new mortgage origination platform did not change the lending decision, but it did change the experience of getting to that decision.
Changing how brokers think about Dudley
A good experience with a lender stays with a broker, particularly when the next client has circumstances where certainty and speed matter. George is clear that cost and suitability must remain at the forefront of any recommendation, but previous experience can become part of that assessment. A broker may be able to present a client with one option based principally on cost and another that comes with recent evidence of a lender being able to deal with the case quickly and efficiently.
That is where the impact of better mortgage technology ultimately becomes more significant than simply making an application form easier to use. Dudley’s criteria got this case through the door. The broker’s packaging helped the underwriter understand it. The process retained the human judgement that a more complex application requires, allowing underwriters to engage directly with brokers where further information was needed. The new mortgage origination platform made the process around those things easier, clearer and less cumbersome.
For the customer, that meant a complex remortgage moved smoothly from application through to offer readiness. For Dudley Building Society, that is perhaps the best measure of whether investment in mortgage technology is working. Not whether a new system has more functionality than the one it replaced, but whether brokers notice the difference and want to use it again.